Key takeaways
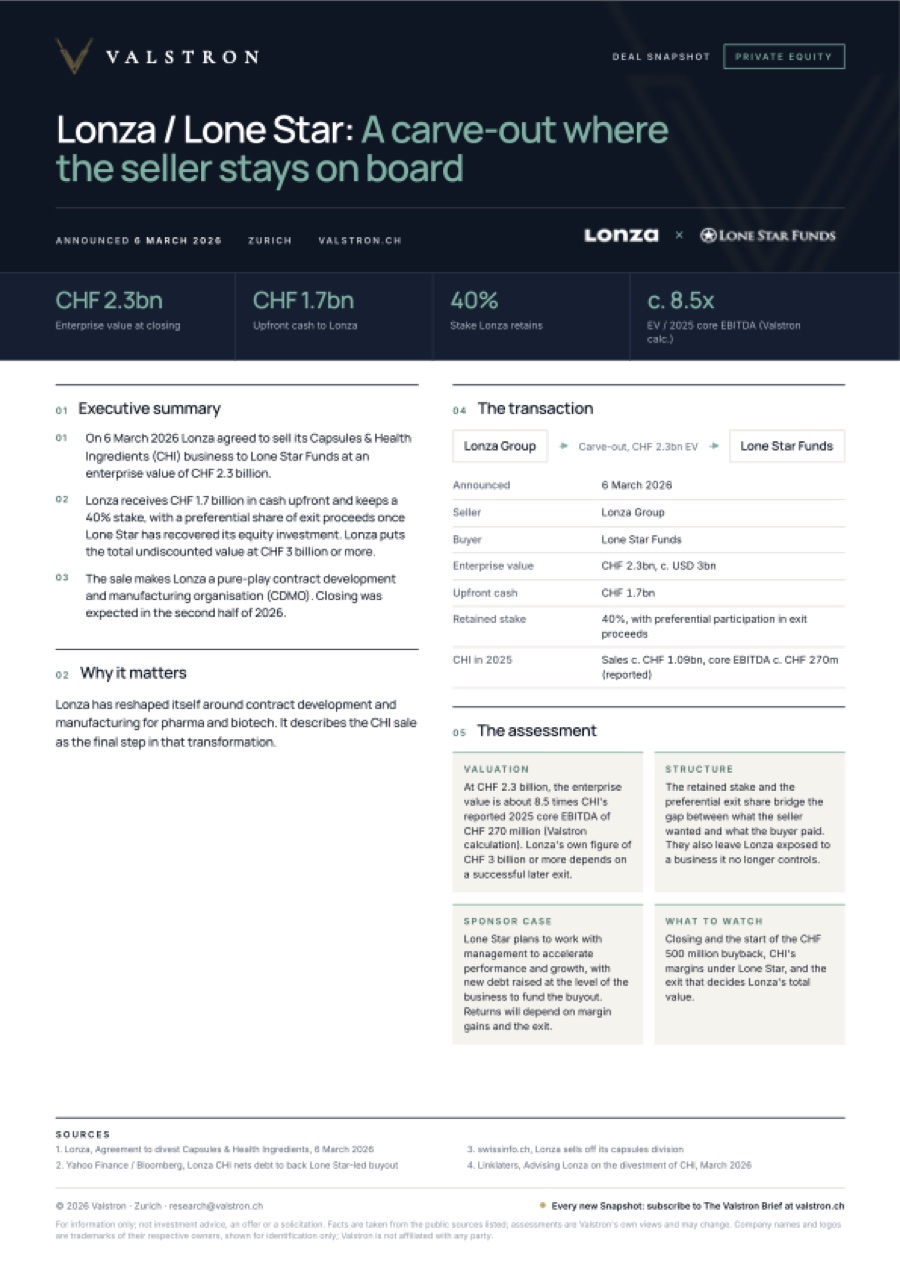
- On 6 March 2026 Lonza agreed to sell its Capsules & Health Ingredients (CHI) business to Lone Star Funds at an enterprise value of CHF 2.3 billion.
- Lonza receives CHF 1.7 billion in cash upfront and keeps a 40% stake, with a preferential share of exit proceeds once Lone Star has recovered its equity investment. Lonza puts the total undiscounted value at CHF 3 billion or more.
- The sale makes Lonza a pure-play contract development and manufacturing organisation (CDMO). Closing was expected in the second half of 2026.
The transaction
 SellerLonza Group
 BuyerLone Star Funds
Result Lonza keeps 40%
| Announced | 6 March 2026 |
|---|---|
| Seller | Lonza Group |
| Buyer | Lone Star Funds |
| Enterprise value | CHF 2.3bn, c. USD 3bn |
| Upfront cash | CHF 1.7bn |
| Retained stake | 40%, with preferential participation in exit proceeds |
| CHI in 2025 | Sales c. CHF 1.09bn, core EBITDA c. CHF 270m (reported) |
| Use of proceeds | Organic growth, bolt-on acquisitions, CHF 500m share buyback |
| Expected closing | Second half of 2026 |
Timeline
- 6 Mar 2026Agreement with Lone Star announced
- Jun 2026Lonza restates figures with CHI as discontinued operations
- H2 2026Closing expected, subject to approvals and separation
The rationale
Lonza has reshaped itself around contract development and manufacturing for pharma and biotech. It describes the CHI sale as the final step in that transformation.
CHI, which includes the Capsugel capsules business, serves pharmaceutical, nutraceutical and nutrition markets, a different business from Lonza's core CDMO work.
Keeping 40% lets Lonza share in value created under Lone Star's ownership, instead of selling everything at a single point in time.
The assessment
Valuation
At CHF 2.3 billion, the enterprise value is about 8.5 times CHI's reported 2025 core EBITDA of CHF 270 million (Valstron calculation). Lonza's own figure of CHF 3 billion or more depends on a successful later exit.
Structure
The retained stake and the preferential exit share bridge the gap between what the seller wanted and what the buyer paid. They also leave Lonza exposed to a business it no longer controls.
Sponsor case
Lone Star plans to work with management to accelerate performance and growth, with new debt raised at the level of the business to fund the buyout. Returns will depend on margin gains and the exit.
What to watch
Closing and the start of the CHF 500 million buyback, CHI's margins under Lone Star, and the exit that decides Lonza's total value.
Source: Lonza, 6 March 2026; total is Lonza's estimate of at least CHF 3bn
 ×
 ×

 ×