Key takeaways
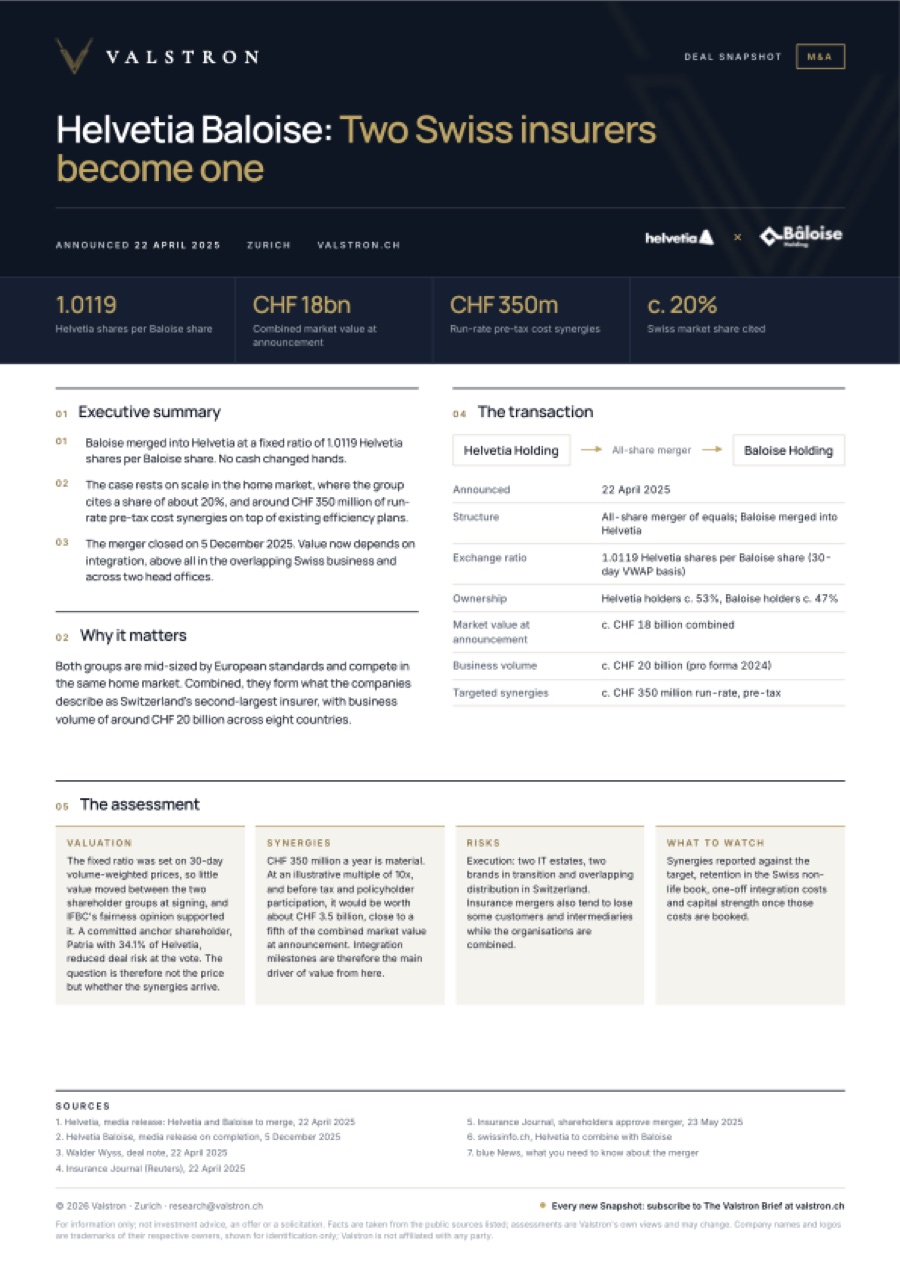
- Baloise merged into Helvetia at a fixed ratio of 1.0119 Helvetia shares per Baloise share. No cash changed hands.
- The case rests on scale in the home market, where the group cites a share of about 20%, and around CHF 350 million of run-rate pre-tax cost synergies on top of existing efficiency plans.
- The merger closed on 5 December 2025. Value now depends on integration, above all in the overlapping Swiss business and across two head offices.
The transaction
 Absorbing companyHelvetia Holding
 Merged into HelvetiaBaloise Holding
Result Helvetia Baloise Holding
| Announced | 22 April 2025 |
|---|---|
| Structure | All-share merger of equals; Baloise merged into Helvetia |
| Exchange ratio | 1.0119 Helvetia shares per Baloise share (30-day VWAP basis) |
| Ownership | Helvetia holders c. 53%, Baloise holders c. 47% |
| Market value at announcement | c. CHF 18 billion combined |
| Business volume | c. CHF 20 billion (pro forma 2024) |
| Targeted synergies | c. CHF 350 million run-rate, pre-tax |
| Anchor shareholder | Patria Genossenschaft, 34.1% of Helvetia, committed to vote in favour |
| Completed | 5 December 2025; new shares listed 8 December 2025 |
| Leadership | Chair Thomas von Planta, CEO Fabian Rupprecht |
Timeline
- 22 Apr 2025Merger of equals announced
- 23 May 2025Shareholders of both companies approve
- 5 Dec 2025Merger completed, Helvetia Baloise Holding formed
- 8 Dec 2025New shares admitted to trading on SIX
The rationale
Both groups are mid-sized by European standards and compete in the same home market. Combined, they form what the companies describe as Switzerland's second-largest insurer, with business volume of around CHF 20 billion across eight countries.
The deal was structured as a merger of equals based on market values. Because it was paid entirely in shares, neither investor base was bought out: both became co-owners of a larger group, Helvetia's holders with about 53% and Baloise's with about 47%.
Management targets around CHF 350 million of run-rate pre-tax cost synergies, before policyholder participation and in addition to existing efficiency plans, and expects dividend capacity to rise by about 20%. Press reports indicated that the savings include job reductions, with the head offices in Basel and St. Gallen most affected.
The assessment
Valuation
The fixed ratio was set on 30-day volume-weighted prices, so little value moved between the two shareholder groups at signing, and IFBC's fairness opinion supported it. A committed anchor shareholder, Patria with 34.1% of Helvetia, reduced deal risk at the vote. The question is therefore not the price but whether the synergies arrive.
Synergies
CHF 350 million a year is material. At an illustrative multiple of 10x, and before tax and policyholder participation, it would be worth about CHF 3.5 billion, close to a fifth of the combined market value at announcement. Integration milestones are therefore the main driver of value from here.
Risks
Execution: two IT estates, two brands in transition and overlapping distribution in Switzerland. Insurance mergers also tend to lose some customers and intermediaries while the organisations are combined.
What to watch
Synergies reported against the target, retention in the Swiss non-life book, one-off integration costs and capital strength once those costs are booked.
Source: Insurance Journal (Reuters), 22 April 2025.
Sources
- Helvetia, media release: Helvetia and Baloise to merge, 22 April 2025
- Helvetia Baloise, media release on completion, 5 December 2025
- Walder Wyss, deal note, 22 April 2025
- Insurance Journal (Reuters), 22 April 2025
- Insurance Journal, shareholders approve merger, 23 May 2025
- swissinfo.ch, Helvetia to combine with Baloise
- blue News, what you need to know about the merger
 ×
 ×
 ×