Key takeaways
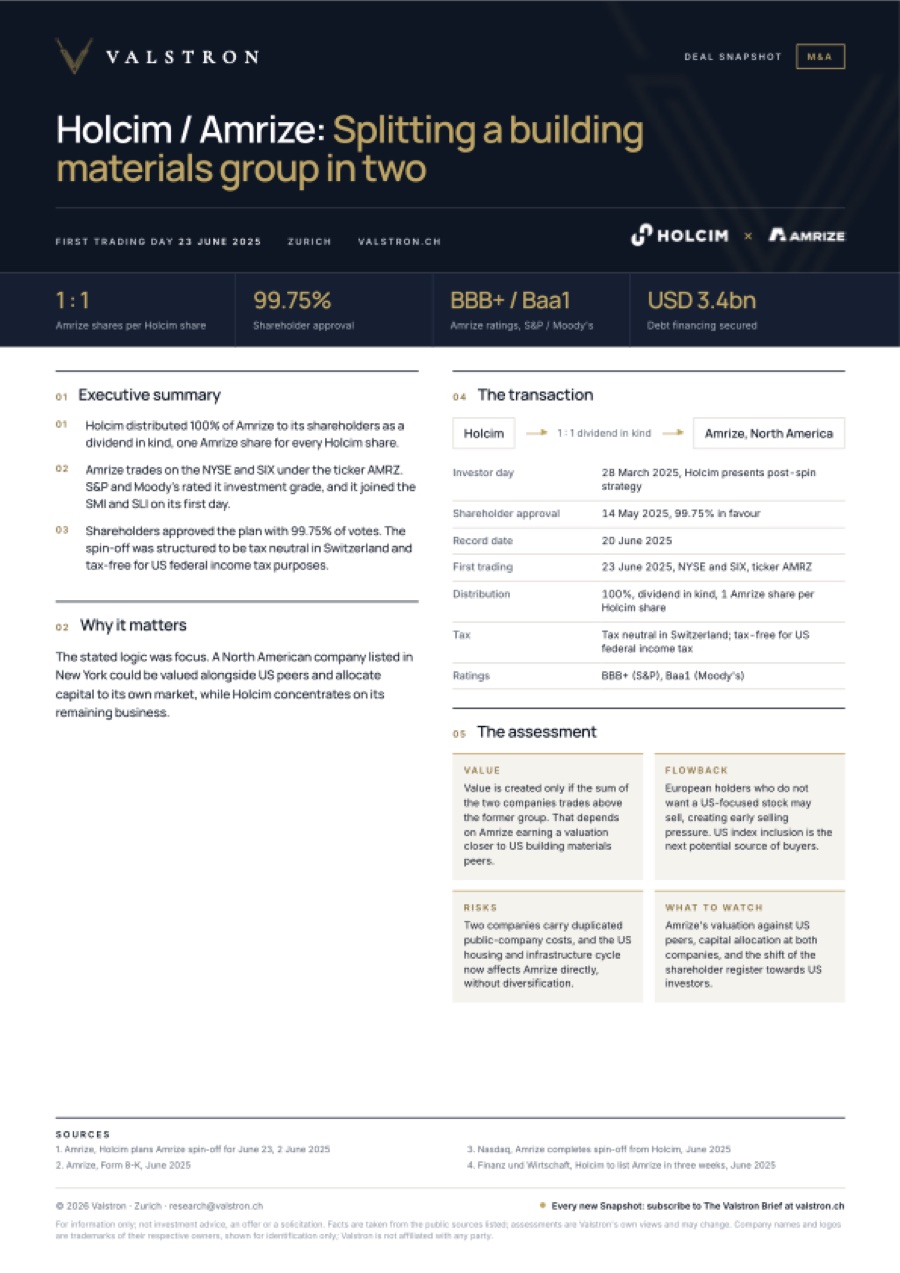
- Holcim distributed 100% of Amrize to its shareholders as a dividend in kind, one Amrize share for every Holcim share.
- Amrize trades on the NYSE and SIX under the ticker AMRZ. S&P and Moody's rated it investment grade, and it joined the SMI and SLI on its first day.
- Shareholders approved the plan with 99.75% of votes. The spin-off was structured to be tax neutral in Switzerland and tax-free for US federal income tax purposes.
The transaction
 ParentHolcim
 Spun offAmrize, North America
Result Two listed companies
| Investor day | 28 March 2025, Holcim presents post-spin strategy |
|---|---|
| Shareholder approval | 14 May 2025, 99.75% in favour |
| Record date | 20 June 2025 |
| First trading | 23 June 2025, NYSE and SIX, ticker AMRZ |
| Distribution | 100%, dividend in kind, 1 Amrize share per Holcim share |
| Tax | Tax neutral in Switzerland; tax-free for US federal income tax |
| Ratings | BBB+ (S&P), Baa1 (Moody's) |
| Financing | USD 3.4bn debt; USD 2bn credit facility, USD 2bn commercial paper |
| Headquarters | Operational HQ Chicago; registered office Zug |
| Indices | Added to SMI and SLI on the first trading day |
Timeline
- 28 Mar 2025Holcim investor day
- 14 May 2025AGM approves the spin-off, 99.75%
- 2 Jun 2025Spin-off date confirmed
- 23 Jun 2025Amrize begins trading on NYSE and SIX
The rationale
The stated logic was focus. A North American company listed in New York could be valued alongside US peers and allocate capital to its own market, while Holcim concentrates on its remaining business.
A spin-off returns a business to the same shareholders instead of selling it. There is no buyer and no price to negotiate, and shareholders decide for themselves which company to keep.
Two listings give access to US investors without forcing Swiss holders out, and inclusion in the SMI and SLI from day one limited forced selling by Swiss index funds.
The assessment
Value
Value is created only if the sum of the two companies trades above the former group. That depends on Amrize earning a valuation closer to US building materials peers.
Flowback
European holders who do not want a US-focused stock may sell, creating early selling pressure. US index inclusion is the next potential source of buyers.
Risks
Two companies carry duplicated public-company costs, and the US housing and infrastructure cycle now affects Amrize directly, without diversification.
What to watch
Amrize's valuation against US peers, capital allocation at both companies, and the shift of the shareholder register towards US investors.
 ×
 ×
 ×